
A reverse mortgage changes the closing math, not your ability to sell. Selling a home with a reverse mortgage in Reston VA is generally possible, and the loan is typically repaid from the sale proceeds at closing. The key question is whether the sale price will cover the current payoff and other costs, and what may remain for you afterward.
Your proceeds depend on the home’s sale price and the loan’s payoff at closing, which may include principal, accrued interest, and fees. An old statement may not show the amount currently due. Before setting a budget for your next move, request an up-to-date payoff from your loan servicer and ask how long it remains valid.
This guide explains how the sale and payoff work, what to confirm before closing, and how to estimate net proceeds. It also covers how to coordinate the servicer, settlement professional, family, and real estate agent. Whether you’re selling in Reston or considering a move elsewhere in Northern Virginia, including Aldie, Leesburg, Middleburg, Ashburn, or Sterling, a plan based on verified figures can help you make informed decisions.
Key Takeaways
- Selling a home with a reverse mortgage in Reston VA is generally possible, but your loan documents and servicer instructions determine the required steps.
- Estimate potential proceeds by accounting for the sale price, verified payoff, liens, and applicable transaction expenses.
- Request an up-to-date payoff statement and confirm how long it remains valid before relying on your sale calculations.
- Contact your servicer early to clarify requirements and align the sale timeline with the closing process.
- Keep roles clear: your agent can support pricing, marketing, offers, and coordination, while the servicer and settlement professional address loan and closing details.
Can You Sell a Reston Home With a Reverse Mortgage? Start With the Answer
Yes, homeowners can generally sell a Reston property with a reverse mortgage. The loan must be addressed as part of the sale, typically through repayment at closing under the loan’s terms. Selling a home with a reverse mortgage in Reston VA doesn’t automatically mean you have to refinance or keep the property until the loan is otherwise paid off.
Your next steps depend on the loan type, signed documents, servicer instructions, and your circumstances. Before choosing a listing date or counting on a certain amount of equity, get loan-specific guidance and a current payoff figure. An estimate alone can’t confirm what will be required at closing or how much may remain.
What a reverse mortgage means when you decide to sell
A reverse mortgage is a loan secured by the home. Unlike a typical mortgage with scheduled monthly principal-and-interest payments from the borrower, the balance generally grows over time according to the loan terms. The Reverse mortgage overview offers background on the basic concept, but your loan documents and servicer determine the details that apply to your sale.
When you sell, the transaction typically triggers repayment of the amount due, using sale proceeds at closing. Your listing agent doesn’t set or verify that amount. Ask the servicer for the current payoff and written instructions, including any requirements or timing details that could affect the transaction. Selling the property is different from refinancing the loan or transferring it to another home. Don’t assume the reverse mortgage moves with you.
Who should be involved before listing in Reston
Bring the right people into the conversation early so sale planning and loan requirements stay aligned. Each professional has a distinct role:
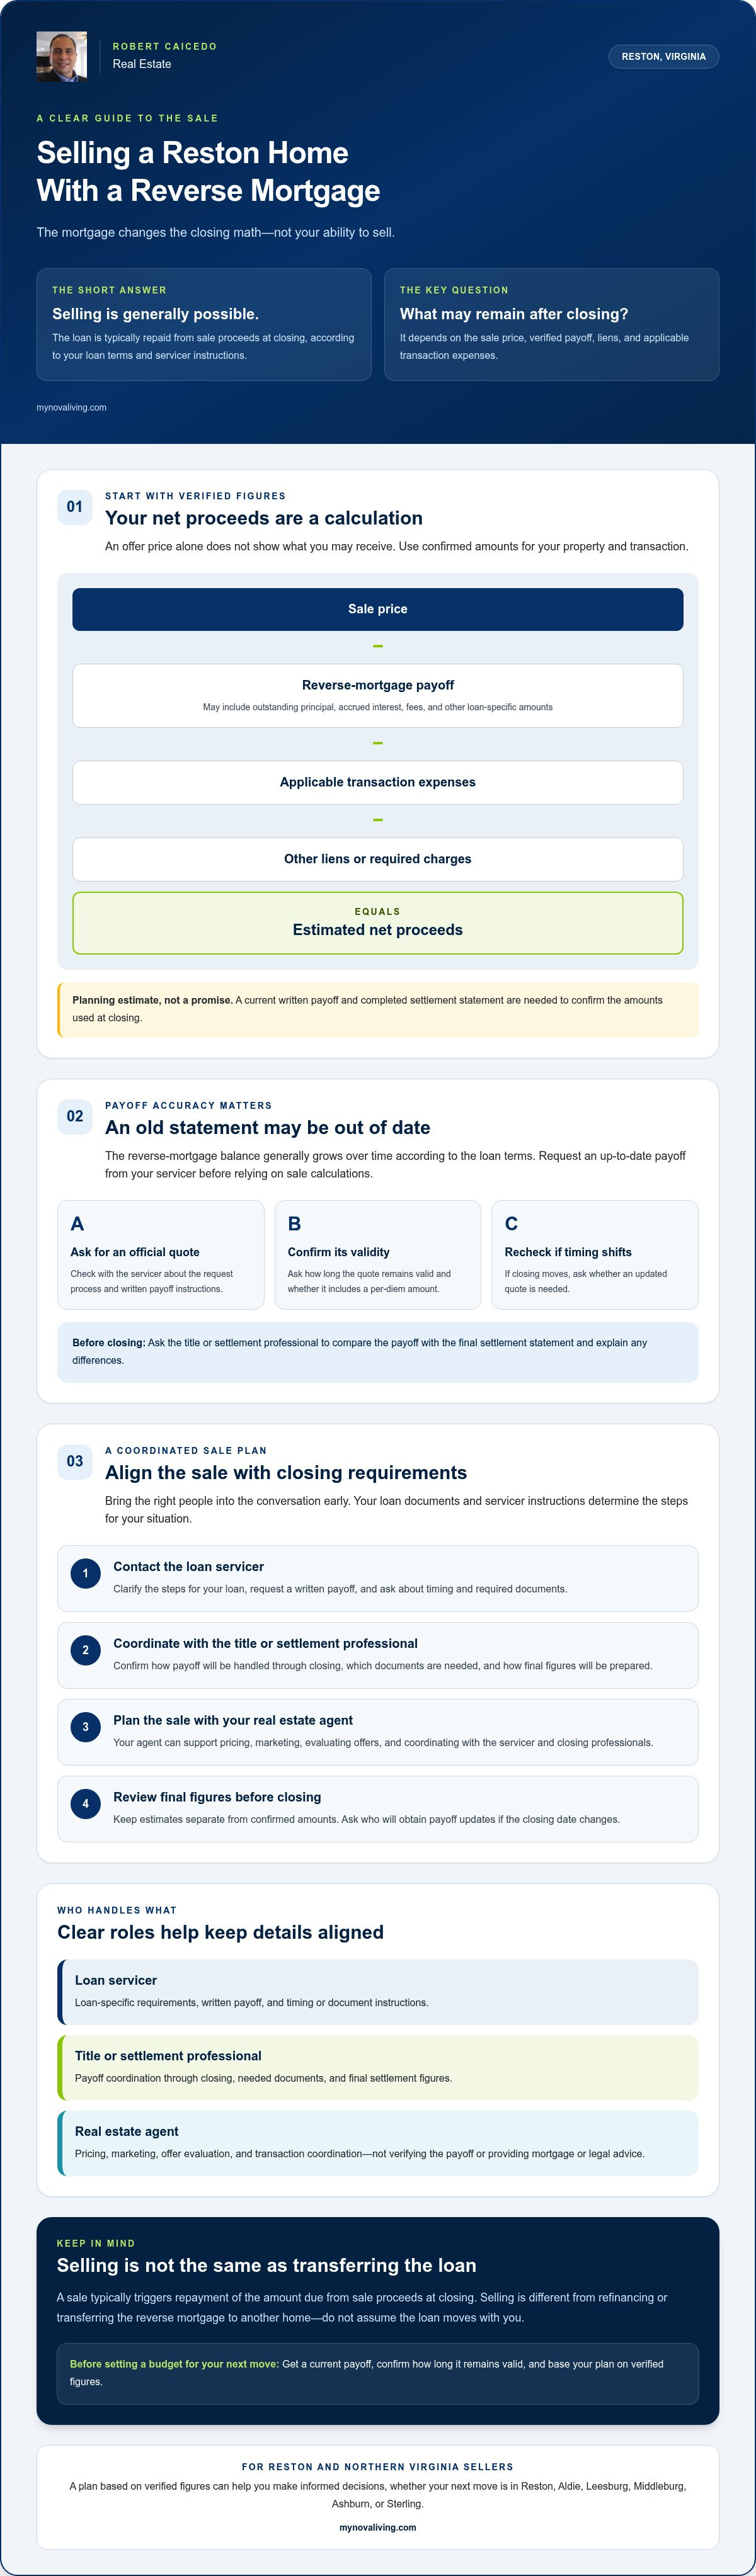
- Loan servicer: Ask what steps apply to your loan, how to request a written payoff, and what timing or documents to plan for.
- Title or settlement professional: Ask how the payoff will be coordinated through closing, what documents are needed, and how final figures will be prepared.
- Reston seller representative: Work with an agent on pricing, marketing, evaluating offers, and coordinating the transaction with the servicer and closing professionals.
Your agent can help keep communication organized, but can’t provide mortgage or legal advice or confirm the loan payoff. Start with the servicer and closing professional, then use their guidance to shape a realistic sale plan. This helps separate confirmed amounts from estimates before you make decisions based on expected proceeds.
How Reverse-Mortgage Payoff and Home-Sale Proceeds Work
Your estimated proceeds depend on more than the offer price. Use this framework to start:
Sale price − reverse-mortgage payoff − applicable transaction expenses − other liens or required charges = estimated net proceeds
This is a planning estimate, not a promise of what you’ll receive. A payoff may include outstanding principal, accrued interest, fees, and other amounts specific to your loan. Transaction expenses and additional liens can also affect the final figure. Use amounts confirmed for your property and transaction rather than general cost assumptions.
The Consumer Financial Protection Bureau explains how a reverse mortgage is handled when a homeowner sells, including why the sale price and loan balance matter. Your servicer’s instructions and closing documents determine how that guidance applies to your situation.
How to request and review a payoff statement
Ask your servicer how to request an official payoff quote and how long it remains valid. Provide the expected closing date and ask whether the quote includes a per-diem amount, which may account for additional interest if closing occurs later. If the date changes, check whether you need an updated quote. Before closing, ask the title or settlement professional to compare the payoff with the final settlement statement and explain any differences.
Keep preliminary estimates separate from confirmed figures. A rough calculation can help you assess an offer, but only a current written payoff and completed settlement statement show the amounts being used at closing. When selling a home with a reverse mortgage in Reston VA, ask who will obtain the payoff, how updates will be handled if the date shifts, and when you’ll receive the final proceeds calculation.
What if the balance is higher than the offer?
Don’t assume what happens next. The steps depend on the loan type, your contract, the sale value, and the servicer’s requirements. If your loan is an FHA-insured HECM, ask the servicer to explain which HUD rules and protections apply to your specific circumstances. Confirm any potential shortfall, required funds, or other options with the servicer and a qualified closing professional before making a decision.
An agent can help you assess pricing, offers, and transaction coordination, but can’t confirm your payoff or provide mortgage or legal advice. If you’re planning a Reston sale, explore seller representation for your Reston home as part of a coordinated plan with your servicer and closing professional.
The Biggest Concern: Will the Reverse Mortgage Leave You With No Equity?
No. A reverse mortgage doesn’t automatically eliminate your equity or determine what you’ll take away from a sale. The outcome depends on the home’s sale price, the loan payoff at closing, any other liens, and transaction expenses. A higher sale price may leave proceeds after those amounts are paid. If the figures are close, the amount remaining may be smaller or none at all.
For a neutral overview of what happens when you sell your home, see the Consumer Financial Protection Bureau’s guidance. Your own result still requires a review of your loan and property-specific closing figures.
How to estimate net proceeds without guessing
Start with a proposed sale price informed by a local comparative market analysis, then replace estimates with written, current figures as they become available. Ask the servicer for a payoff quote and confirm its expiration date and whether it reflects your expected closing date. Have the settlement professional identify recorded liens, prorations, and transaction charges that may affect your proceeds.
Hypothetical example only: If a home sold for $700,000, the verified loan payoff were $420,000, applicable transaction expenses totaled $35,000, and another lien required $5,000, the estimated amount remaining would be $240,000. These figures are for illustration only. They aren’t Reston market data, a cost estimate, or a prediction of your result.
Use this calculation to organize questions, not to make a financial decision. The final settlement statement may differ from an early estimate if the closing date, payoff, or other charges change.
Reston and Fairfax County details to verify
Property details can affect the paperwork and closing figures. Check whether your home is part of a homeowners association or condominium and ask whether resale documents or related requirements apply. Don’t assume every Reston property has the same obligations.
Ask the settlement professional to verify applicable Fairfax County and Virginia closing requirements for your specific transaction. Have them review property-specific taxes, assessments, and recorded liens rather than assuming these are uniform across the area.
Before making plans based on expected proceeds, request written payoff confirmation from the servicer and review the closing figures with the settlement team. A Reston seller representative can help with pricing, offers, and transaction coordination, while the servicer and closing professional confirm loan and settlement details. This keeps your estimate grounded in verified information.
How to Sell a Reston Home With a Reverse Mortgage: A Step-by-Step Plan
A clear sequence helps keep the sale, loan requirements, and closing details moving together. Contact the servicer before choosing a listing date or accepting an offer. Your reverse-mortgage terms and the servicer’s instructions can affect what information the closing team needs and when it needs it.
Before listing: prepare the loan and property information
Gather the documents and details that will help you get reliable answers and prepare the home for market:
- Find your loan records. Locate the latest reverse-mortgage statement, original loan documents, servicer contact details, and any previous payoff information. Treat older payoff figures as historical, not as current closing amounts.
- Ask the servicer about the sale process. Request current sale procedures, instructions for obtaining an official payoff, and information about any forms, reviews, or timing steps that apply to your loan.
- Organize property records. Keep available tax, assessment, association, or condominium information together for the closing professional to review. Ask which documents are needed for your property.
- Plan the listing with a Reston representative. Discuss the home’s condition, pricing, and marketing approach. A seller representative can help evaluate offers and coordinate transaction details, while the servicer remains the source for loan-specific instructions.
Keep correspondence and records in one place, such as a dedicated folder or secure digital file. This makes it easier to answer questions consistently and share requested documents with the right professionals.
Under contract through closing: coordinate every handoff
Once you have a signed contract, promptly share it and the anticipated closing date with the servicer and settlement professional. Confirm who will request and deliver the payoff, what information is still needed, and how an updated quote will be handled if the closing date changes.
- Check that the payoff covers the expected closing date and ask whether any additional daily amount applies.
- Confirm required documents and signatures with the servicer and settlement professional. Ask directly about any occupancy-related instructions that may apply to your circumstances.
- Review the settlement statement before closing. Make sure the loan payoff, other listed charges, and any remaining proceeds are clearly shown.
- Ask the settlement professional how any proceeds due to you will be disbursed and what final confirmation you’ll receive.
For selling a home with a reverse mortgage in Reston VA, early coordination means fewer unanswered questions as closing approaches. Your agent can help connect the transaction’s moving parts, but loan and legal questions belong with the servicer and qualified closing professionals.
For an overview of the real estate support available during the sale, explore seller representation for your Reston home.
Choose Your Reston Sale Team and Move Forward With Confidence
A well-coordinated sale starts with clear roles. Your real estate agent helps develop a pricing strategy, market the home, review offers, and coordinate transaction communication. The loan servicer explains the reverse mortgage’s requirements, payoff process, and loan-specific instructions. A title or settlement professional prepares closing figures, coordinates the payoff, and verifies applicable requirements for your transaction.
These roles complement one another, but they aren’t interchangeable. An agent can help keep information moving between the people involved in the sale, but shouldn’t represent themselves as your lender, loan servicer, or attorney. Direct mortgage questions to the servicer and legal questions to a qualified attorney.
Questions to ask before hiring a listing agent
Choose someone who can explain how they’ll support your sale and communicate through closing. Ask prospective agents:
- How will you develop a pricing strategy using current Reston market evidence for my property?
- How will you communicate offers, response deadlines, and transaction updates?
- How do you coordinate with the loan servicer and title or settlement team, and what information do you need from me?
- How will you help me evaluate offers without treating an estimated payoff or proceeds figure as confirmed?
- Can you clarify which questions belong with the servicer or settlement professional rather than the agent?
Look for a clear process, not a promise of a particular sale price, closing date, or amount of proceeds. When selling a home with a reverse mortgage in Reston VA, dependable coordination means knowing who will answer each question and how updates will reach you.
Your next steps for a prepared, well-coordinated sale
Gather basic property details and your reverse-mortgage documents. Contact the servicer for sale procedures and current loan information before setting firm expectations about the money you may receive. Then ask a Reston seller representative for a property-specific pricing conversation and an explanation of the representation process, including how communication and offer updates will work.
Robert Caicedo Real Estate provides seller representation in Reston, with support for pricing, marketing, offers, and transaction coordination. The firm can coordinate with the servicer and closing professionals, while loan-specific guidance comes from the servicer and closing details from the settlement team.
To discuss your property and goals, contact Robert Caicedo Real Estate about your Reston home sale.
Plan Your Reston Sale With Clear Next Steps
Selling a home with a reverse mortgage in Reston VA is generally possible, but the loan payoff and sale expenses shape what may remain for you. Start by asking your servicer for current written instructions and payoff information. Then work with a settlement professional to confirm closing figures, including any property-specific charges or liens.
A clear team can make the process easier to organize. Your real estate agent can help with pricing, marketing, offers, and transaction coordination. The servicer explains loan requirements, while the settlement professional handles closing details. Keep those roles clear, and base financial decisions on verified figures rather than early estimates.
Seller representation is the primary service of Robert Caicedo Real Estate, and Reston is within its stated service area. The firm is affiliated with Spring Hill Real Estate, LLC. If you’re ready to discuss your property and sale goals, discuss your Reston home sale with Robert Caicedo Real Estate.
With the right information and a well-coordinated plan, you can take your next step with greater confidence.
Frequently Asked Questions
Is it possible to sell a home with a reverse mortgage in Reston, VA?
Yes, a homeowner can generally sell a Reston home with a reverse mortgage, and the loan is typically addressed through closing. The exact requirements depend on your loan documents, circumstances, and servicer instructions. Contact the servicer early for loan-specific steps and an official payoff figure. Coordinate with a settlement professional about closing documents and figures, and keep your listing agent informed so sale planning can proceed using confirmed information.
What happens to a reverse mortgage when the home is sold?
Sale proceeds are generally used to address the reverse-mortgage payoff through closing, subject to the loan documents and servicer instructions. Any amount remaining depends on the verified sale price, payoff, liens, and transaction expenses. Review the final settlement statement to see how the closing figures are applied and whether proceeds are due to you. Your real estate agent can coordinate sale details, but the servicer provides the official loan payoff.
How do I get a reverse-mortgage payoff amount before selling?
Contact your loan servicer and request a written payoff quote for your expected closing date. Ask when the quote expires and whether it includes any additional daily amount that could apply if closing shifts. If your date changes, check whether you need an updated quote. Don’t rely on an old account balance as the final payoff. Ask the settlement professional to compare the current payoff with the closing statement before the transaction is finalized.
What happens if the reverse-mortgage balance is more than the home sells for?
The outcome depends on the mortgage type, loan terms, sale price, and any protections that apply. If your loan is an FHA-insured HECM, ask the servicer to explain the current HUD rules and procedures for your specific situation. Don’t assume a shortfall will be forgiven or that you must pay it yourself. Request case-specific guidance from the servicer and review the options with a qualified settlement professional or attorney, as appropriate.
Can heirs sell a Reston home after the owner with a reverse mortgage dies?
Heirs may be able to sell the home, but they should contact the loan servicer promptly to confirm applicable deadlines, required documents, and available options. Requirements depend on the loan and the circumstances, so don’t rely on a universal timeline. A qualified attorney or settlement professional can help address estate or closing questions where appropriate. A real estate agent can assist with marketing and sale coordination for the Reston property.
How much equity will I keep after selling a home with a reverse mortgage?
There’s no reliable universal amount. Your estimated proceeds depend on the expected sale price, current written payoff, liens, and transaction expenses. Ask a local agent to help develop a property-specific pricing estimate, then work with a settlement professional to identify applicable closing figures and confirm the loan amount with the servicer. For a Reston home, use verified figures for that property and transaction, and don’t treat an estimate as guaranteed proceeds.


