
Slashing a home's list price isn't always the smartest financial move you can make in the District. When you face the reality of closing costs ranging between 3.0% and 4.5% of your purchase price, largely driven by D.C.'s 1.45% recordation tax on homes $400,000 and above, sticker shock can quickly set in. You want to protect your liquid capital, leaving you to ask: what is a seller credit and how does it work in a DC real estate transaction to give you an edge?
You already know that claiming your ideal rowhouse or modern condominium shouldn't mean draining your savings before you even unpack. That's where seller subsidies enter the picture. Instead of an ordinary price drop that only trims pocket change from your monthly payment, credits can cover steep settlement charges or fund a mortgage rate buydown to create immediate breathing room. In this guide, you'll discover how to leverage local GCAAR contract clauses, respect strict lender contribution limits, and negotiate a frictionless, win-win transaction that keeps your capital intact.
Key Takeaways
- Understand what is a seller credit and how does it work in a DC real estate transaction to offset substantial settlement charges without weakening your offer.
- See how closing subsidies appear on your final settlement statement, turning mandatory municipal transfer and recordation taxes into seller-assisted savings.
- Compare immediate cash-to-close reductions against dynamic financing strategies, such as a 2-1 buydown that lowers your monthly payment during your first two years in your home.
- Uncover strict lender contribution caps across conventional, FHA, and VA loans while safeguarding your purchase against unexpected appraisal gap risks.
- Discover how partnering with an attentive advisor ensures smooth contract negotiations and turns complex financial terms into a curated, frictionless purchase experience.
Demystifying Seller Credits in the DC Real Estate Market
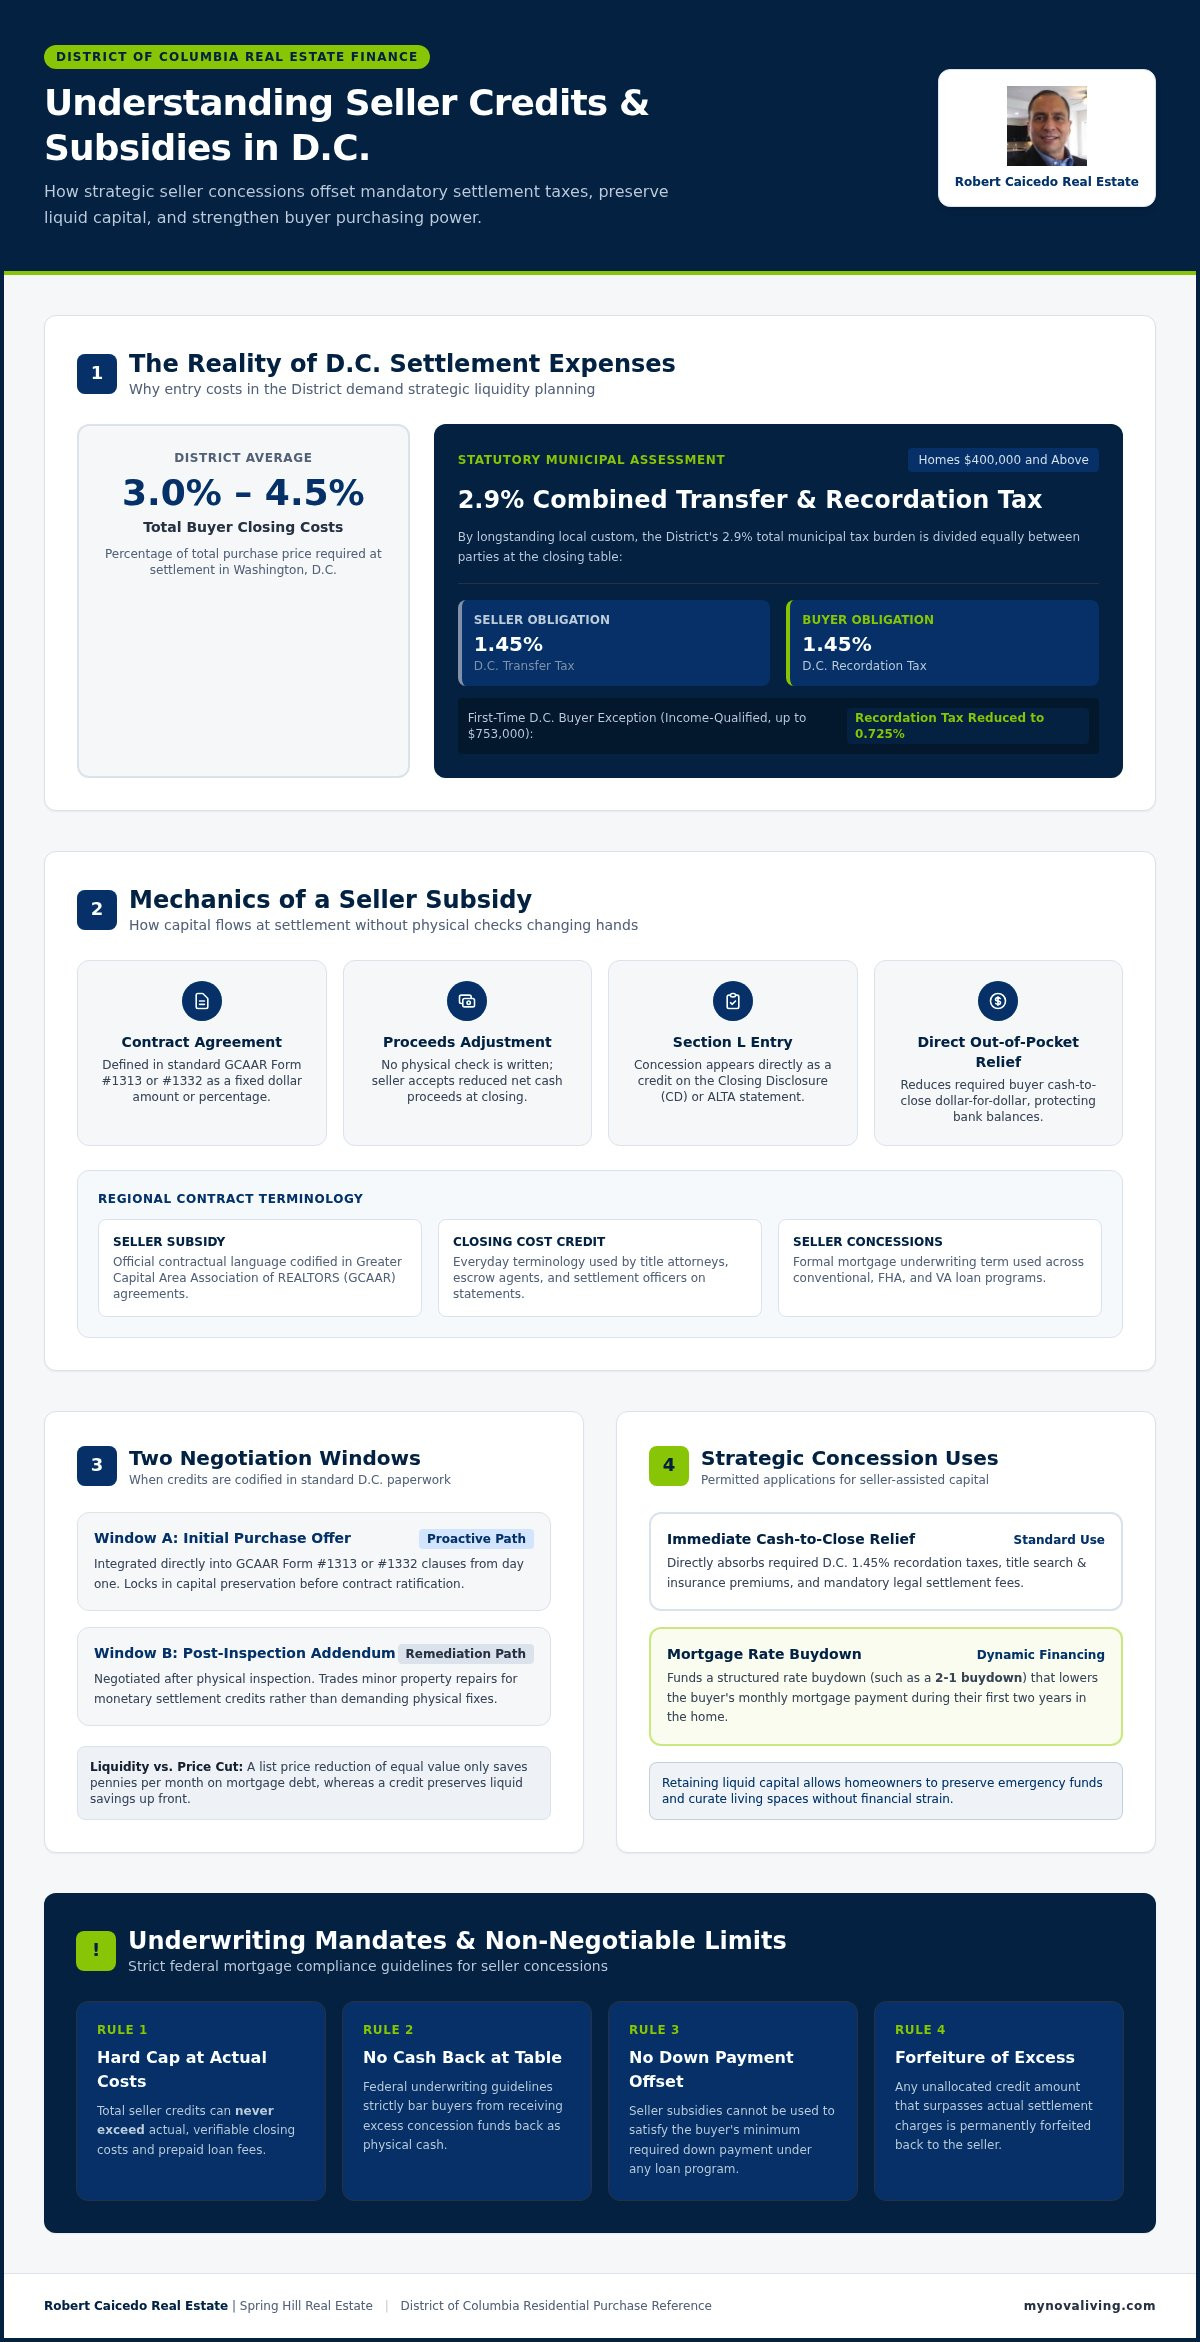
A seller credit is a contractual agreement where the property seller agrees to allocate a portion of their proceeds toward your settlement costs. While national finance blogs often claim these concessions exist strictly to resolve post-inspection repair flaws, the reality in Washington, D.C., is entirely different. Here, credits serve primarily as a strategic financing mechanism designed to offset substantial transaction costs. If you are exploring what is a seller credit and how does it work in a DC real estate transaction, the most critical element to realize is that no physical check changes hands. Instead, the seller accepts a reduction in their net proceeds at the closing table, which directly decreases your cash-to-close requirement.
You can establish this concession during two distinct stages of the acquisition. The most proactive path involves including a credit request within your initial offer to make your liquid capital stretch further from day one. Alternatively, you can negotiate a subsidy post-inspection via an addendum, trading minor property deficiencies for settlement credits rather than demanding physical repairs before settlement.
Why DC Buyers Prioritize Credits
Stepping into a historic Capitol Hill rowhouse or a sleek Dupont Circle penthouse represents a refined lifestyle upgrade, but entry costs remain steep. Buyers in the District routinely face closing fees between 3.0% and 4.5% of the total purchase price. Rather than depleting personal reserves to cover these mandatory administrative fees, an intentional credit allows for genuine liquidity preservation. Retaining that hard-earned capital gives you immediate freedom to curate your living space, commission custom interior design, and establish emergency reserves without financial strain.
Common Synonyms You'll See in GCAAR Contracts
Understanding regional legal terminology is essential as you move through the standard real estate closing process. When drafting regional paperwork, you will encounter distinct terms used almost interchangeably:
- Seller Subsidy: The official contractual term codified in Greater Capital Area Association of REALTORS (GCAAR) agreements, designating a specific dollar figure or percentage allocated to the buyer.
- Closing Cost Credit: Everyday language frequently used by lenders, title attorneys, and settlement officers to describe the final line item offsetting buyer settlement fees.
- Seller Concessions: Federal mortgage terminology adopted across conventional, FHA, and VA underwriting guidelines to monitor financial limits.
Knowing what is a seller credit and how does it work in a DC real estate transaction empowers you to craft a modern, balanced contract that protects your investments while maintaining an exceptionally competitive profile.
The Mechanics of a Seller Subsidy in Your Transaction
When settlement arrives, your negotiated concession transforms into a transparent, dollar-for-dollar deduction on your Closing Disclosure (CD) or ALTA settlement statement. You will see the total amount entered under Section L as a credit against your closing obligations. Fully appreciating what is a seller credit and how does it work in a DC real estate transaction requires examining the District's tax architecture. For residential properties priced at $400,000 and above, D.C. assesses a combined 2.9% transfer and recordation tax. By long-standing local custom, parties divide this burden evenly: the seller covers the 1.45% transfer tax, while you pay the 1.45% recordation tax. First-time buyers meeting strict income guidelines on homes up to $753,000 can reduce that recordation fee to 0.725%, but the expense remains significant.
Your closing subsidy directly absorbs these municipal taxes, title insurance, and settlement fees. Underwriting mandates dictate one non-negotiable parameter: total credits can never exceed your actual, verifiable closing costs. Federal guidelines bar you from taking excess funds as cash at the closing table, and subsidies cannot fund your minimum down payment. Ensuring your credit matches actual charges prevents forfeiting unallocated funds back to the seller.
Navigating the GCAAR Sales Contract
District transactions rely on standardized forms crafted by the Greater Capital Area Association of REALTORS (GCAAR). Form #1313 and Form #1332 feature explicit Seller Subsidy clauses defining your concession as a fixed dollar figure or percentage. The text states that the seller pays toward your allowable settlement fees, discount points, or buydowns as sanctioned by your lender. Robert Caicedo drafts precise contract phrasing that aligns with Fannie Mae interested party contribution limits, ensuring your financing proceeds without eleventh-hour bureaucratic hurdles. If you want tailored representation that safeguards every dollar of your purchase, explore how Caicedo structures acquisitions via buyer representation in D.C.
The Role of the Settlement Agent
Your title attorney serves as the impartial financial orchestrator. They review the purchase contract, verify lender guidelines, and generate an exact settlement net sheet for both sides. The title team tallies transfer taxes, per diem interest, recording charges, and prepaid escrows before applying your credit directly against the total. This rigorous pre-closing reconciliation ensures the seller's net proceeds decrease appropriately and your final wire transfer reflects exact figures with total clarity.
Strategic Advantages: Closing Costs vs. Mortgage Rate Buy-downs
Negotiating a concession is only half the victory; allocating it effectively determines your ultimate return. When mastering what is a seller credit and how does it work in a DC real estate transaction, your primary decision centers on a clear choice: take immediate cash savings at settlement, or redirect those funds toward a mortgage rate buydown. While legacy real estate advice often treats rate buydowns as rare novelties, modern buyers deploy them routinely to manage monthly carrying costs without depleting their liquid wealth.
The contemporary favorite among luxury condo and rowhouse purchasers is the temporary 2-1 buydown. This structure reduces your effective mortgage rate by 2.0% in your first year and 1.0% in your second year, returning to the full fixed note rate in year three. Funding an escrow deposit of roughly 2.0% to 2.5% of the loan amount via a seller subsidy saves you hundreds of dollars each month during your initial settlement period. You can verify how these credits appear alongside financing fees by reviewing the CFPB Closing Disclosure explainer. For buyers planning to hold property for a decade or more, permanent discount points offer another route. Committing 1% of the loan balance per point typically reduces the note rate by 0.25% across the entire 30-year lifecycle, saving tens of thousands in cumulative interest.
When to Choose Cash at Closing
Opting for a direct credit against your immediate settlement expenses is ideal when liquid capital preservation is your highest priority. If you intend to furnish your new residence immediately, commission custom architectural millwork, or simply preserve cash reserves for investment peace of mind, taking your credit as cash relief delivers instant gratification. It also shields buyers who are operating near their maximum allowable liquid limits. Aligning these calculations requires experienced counsel, making Strategic Buyer Representation an indispensable asset during contract negotiations.
When to Choose a Rate Buy-down
Electing a buydown transforms the seller's money into ongoing lifestyle ease. By using concessions to subsidize your monthly payment, you protect predictable monthly cash flows while qualifying for a property that fits your standard of living. Sophisticated investors and high-earning professionals frequently prefer this path, preserving their own liquid reserves for high-yield market vehicles while letting the seller fund their lower monthly housing expense.
Evaluating what is a seller credit and how does it work in a DC real estate transaction through this lens allows you to craft a modern, financially tailored strategy that elevates your everyday living experience.
Navigating Lender Limits and Negotiation Tactics
When examining what is a seller credit and how does it work in a DC real estate transaction, you must understand that underwriters establish rigid boundaries. Lenders regulate interested party contributions (IPCs) based on loan program and down payment size. On a conventional loan for a primary residence, putting down less than 10% caps seller credits at 3% of the purchase price. Providing 10% to 24.99% down unlocks a 6% limit, while placing 25% or more expands allowable credits to 9%. FHA loans permit up to 6%, while VA guidelines limit concessions for buydowns and debt payoffs to 4%. For investment property purchases, regulations enforce a strict 2% maximum regardless of equity.
Lender Rules You Must Know
Surplus credits vanish at settlement. Lenders prohibit you from walking away from the closing table with unused credit pocketed as cash. If negotiated subsidies exceed your verified settlement costs, the unallocated balance defaults straight back to the seller. Outsized credit figures can also trigger underwriting red flags, prompting auditors to question whether the purchase price was artificially elevated. Early, transparent communication with your loan officer prevents these costly oversights.
Negotiating the Credit Without Weakening Your Offer
To a listing party, bottom-line net proceeds reign supreme. Submitting an offer of $1,000,000 with a $20,000 credit yields essentially the same net return as a clean $980,000 bid. However, increasing your purchase price to finance a subsidy introduces appraisal risk. If you contract a Navy Yard residence at $1,000,000 with a $20,000 subsidy but the property appraises for only $980,000, the lender recalculates loan amounts and allowable subsidies on that lower figure, leaving you to bridge an unexpected appraisal gap.
In competitive enclaves like Georgetown or Dupont Circle, requesting credits in your initial offer can weaken your profile against multiple bids. You can protect your competitive edge by submitting a clean offer and negotiating credits after the home inspection. Agreeing to accept the property in its current state in exchange for a settlement subsidy removes the hassle of contractor delays before closing while preserving your liquid capital. Mastering what is a seller credit and how does it work in a DC real estate transaction allows you to craft terms that appeal to listing agents while guarding your bottom line. To structure an agile acquisition strategy that elevates your purchasing power, partner with Robert Caicedo for elite buyer representation.
Partnering with Robert Caicedo for a Sophisticated DC Purchase
Mastering what is a seller credit and how does it work in a DC real estate transaction transforms standard contract terms into an intentional financial strategy. Executing this strategy requires more than basic paperwork. You deserve an attentive advisor who translates dense legal clauses into an effortless home-buying journey. Affiliated with Spring Hill Real Estate, LLC, Robert Caicedo delivers elite representation across Washington, D.C., and Northern Virginia, helping buyers navigate multi-party transactions with total confidence.
Securing an optimal subsidy demands thorough mathematical preparation. Robert's team reconciles settlement quotes against local transfer taxes and loan caps, ensuring your contract remains completely compliant. This organized, detail-first guidance removes traditional industry frictions, letting you focus on the lifestyle and architectural elements that drew you to the District in the first place.
Beyond the Transaction: A Lifestyle Approach
Your residence is more than an asset; it is the physical foundation for your everyday routine. Robert pairs a deep appreciation for curated living spaces with extensive background in land development and investment property consulting. This dual perspective proves invaluable when structuring concessions. Whether evaluating long-term appreciation in a historic Logan Circle rowhouse or exploring New Construction Homes in Northern Virginia, Caicedo evaluates each dollar through the lens of your overarching portfolio and immediate personal comfort.
Ready to Secure Your DC Home?
Navigating the District's fast-paced market requires proactive positioning. The most successful transactions begin long before drafting an offer letter. By scheduling a private strategy consultation, you can align financing choices, contract language, and negotiation tactics into a cohesive purchase plan. If you are ready to fully leverage what is a seller credit and how does it work in a DC real estate transaction, contact Robert Caicedo today to initiate your curated acquisition.
Master Your Closing Strategy for a Seamless DC Move
Approaching your purchase with clear intention turns closing subsidies into an exceptional financial advantage. Understanding what is a seller credit and how does it work in a DC real estate transaction gives you the power to preserve vital liquidity, offset local transfer taxes, or lower your ongoing monthly carrying costs through an intentional rate buydown. When structured cleanly within standard GCAAR agreements, these concessions create an effortless path to homeownership while fully respecting lender limits.
Executing this balance requires a dedicated partner who understands every nuance of regional contracts. As an independent real estate consultant affiliated with Spring Hill Real Estate, LLC, Robert Caicedo blends seasoned expertise across D.C. and Northern Virginia residential markets with strategic consulting in land development and investment acquisitions. With attentive guidance handling the complex math behind the scenes, you can step into your new residence with total confidence. Discover how our sophisticated buyer representation can optimize your next D.C. purchase.
Frequently Asked Questions
Can a seller credit be used for a down payment in DC?
No, federal and agency lending guidelines strictly prohibit applying seller credits toward your minimum cash down payment. Subsidies can only cover allowable closing costs, title charges, municipal transfer taxes, prepaids, and discount points. If you need assistance meeting your down payment requirements, discuss local down payment assistance programs or gift funds with your lender before finalizing your purchase offer.
What happens if my seller credit exceeds my total closing costs?
Any excess funds are automatically forfeited back to the seller because lenders prohibit buyers from receiving cash back at settlement. If your closing expenses end up lower than the negotiated credit, work with your agent to redirect the remaining amount. You can often allocate surplus funds toward prepaids, additional discount points, or modify the contract purchase price before closing day arrives.
Are seller credits common in the Washington D.C. luxury market?
Yes, luxury sellers in D.C. frequently offer closing credits to facilitate smooth transactions without slashing published listing prices. In high-end neighborhoods like Georgetown or Kalorama, sellers prefer granting a closing credit over reducing their benchmark list price. This approach protects neighborhood property values while giving you valuable capital flexibility to fund bespoke interior improvements or rate buydowns immediately upon possession.
How do lender limits for seller concessions work in 2026?
Lender caps depend on your financing vehicle and equity level. Conventional loans limit seller credits to 3% for down payments under 10%, 6% for down payments between 10% and 24.99%, and 9% for 25% or more down. FHA loans permit up to 6%, while VA loans cap certain seller concessions at 4%. Investment purchases remain capped at a strict 2% regardless of down payment.
Is a seller credit better than a price reduction?
A seller credit is often far superior if you want to optimize your liquidity and immediate purchasing power. Understanding what is a seller credit and how does it work in a DC real estate transaction highlights this distinction clearly. Lowering the price slightly trims a few dollars off your monthly payment, whereas a credit immediately saves thousands in cash-to-close or funds a temporary interest rate buydown.
Who pays the recordation tax in DC when a credit is involved?
By local custom in Washington, D.C., the buyer customarily pays the 1.45% recordation tax on homes $400,000 or above, while the seller pays the 1.45% transfer tax. When a seller credit is negotiated, the buyer technically remains responsible for that tax line item, but the negotiated credit directly offsets that specific settlement charge on your final Closing Disclosure.
Can I ask for a seller credit after the home inspection?
Absolutely. Negotiating a subsidy through a GCAAR inspection addendum is a standard and effective strategy in the District. If an inspection reveals needed structural or mechanical repairs, requesting a credit allows you to choose your own vetted contractors after closing. Sellers often prefer this method because it eliminates the hassle of coordinating physical repair work under tight pre-closing deadlines.
Does a seller credit affect my mortgage interest rate?
A credit does not inherently alter your interest rate unless you intentionally apply those funds toward mortgage discount points or a temporary buydown. Knowing what is a seller credit and how does it work in a DC real estate transaction lets you use concessions strategically. Applying your subsidy to purchase discount points lowers your monthly payments and saves thousands over the life of your loan.


